

MoneyGram® Money Transfers App

- 51.85K Reviews
- 4.6
- Downloads
- 5,000,000+
Our take on MoneyGram® Money Transfers App from Appgk
Sending money across borders can feel unnecessarily complicated, especially when the person receiving it needs the funds quickly or does not use the same banking services I do. MoneyGram® Money Transfers App takes a familiar money-transfer service and puts the main steps on a phone. I found it most useful when I already knew who I was sending to, understood the destination country’s requirements, and wanted to begin the transfer without visiting an agent immediately.
The app is a free finance tool from MGI, aimed at international currency, money, and wire transfers. It has been available since May 13, 2014, and its broad adoption is reflected in an average rating of 4.6 from around 128 thousand ratings, with more than 5 million installs. Those figures do not automatically make every transfer effortless, but they do suggest that this is an established option rather than a small experimental wallet.
How the everyday transfer workflow feels
My preferred way to use the app starts before I open it. I collect the recipient’s legal name exactly as it should appear, confirm the destination country, and decide whether the recipient needs a bank deposit, mobile-related delivery option, or cash pickup where available. That preparation matters because a spelling difference or an unsuitable delivery method can create more trouble than the app itself.
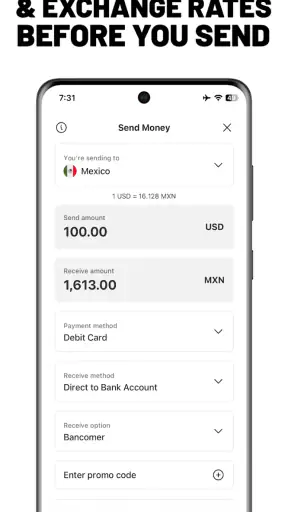
Inside the app, I treat the first transfer as a careful setup rather than a race. I enter the destination and amount, review the available delivery choices, and pay close attention to the final summary before confirming. The important habit is to check the recipient details and the total cost together. Looking only at the amount the recipient receives can hide the practical impact of fees or exchange-rate differences.
Best Parts of MoneyGram® Money Transfers App
Things to Keep in Mind About MoneyGram® Money Transfers App
The safest workflow is to pause at the final review screen, even when the transfer feels routine. I verify the recipient’s name, destination, delivery method, and amount in one pass. This is especially important for cash pickup, where the receiver may need to present identification and match the transfer information accurately. A quick reread is far cheaper than trying to correct a completed transaction.
For a realistic example, imagine sending money to a relative abroad at the end of the month. I would first message the relative to confirm the exact name they will use for collection and whether a bank deposit or cash pickup is more convenient. Then I would create the transfer in the app, compare the available options, save the confirmation details, and tell the recipient when and how to collect the funds. The app handles the transaction steps, but the communication around the transfer remains my responsibility.
News and Features Related to MoneyGram® Money Transfers App

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo

News
Moovit Review: A More Reliable Way to Navigate Everyday Transit

News
Mastering Screen Recorder - XRecorder: Pro Tips for Mobile Video
This distinction is easy to overlook. MoneyGram is not a substitute for checking whether the recipient can access a particular delivery method in their location. It is also not a budgeting app or a shared family ledger. I use it for the transfer itself and keep my own record of the purpose, amount, and recipient so that recurring payments do not become a confusing list of similar transactions.
What I check before sending
The first decision is delivery speed versus convenience. Cash pickup can be useful when the recipient does not have a suitable bank account, while a deposit may be more convenient for someone who wants to avoid traveling to an agent. The right choice depends on the recipient’s circumstances, not simply on which option appears first in the app.
Don't want to read the full review?
The second decision is currency. I read the amount the sender pays and the amount the recipient receives rather than assuming the exchange rate tells the whole story. A transfer that looks inexpensive at the start may feel different after the total is converted. I also avoid making assumptions based on a previous transfer, because destination, delivery type, and payment method can affect the final calculation.
The third decision is timing. If the recipient needs the money for a bill or an urgent purchase, I do not promise an exact arrival time based solely on the app’s initial estimate. I tell the recipient which method I selected and keep the transfer reference available. That creates a clearer handoff if either of us needs to check the transaction later.
Screenshots
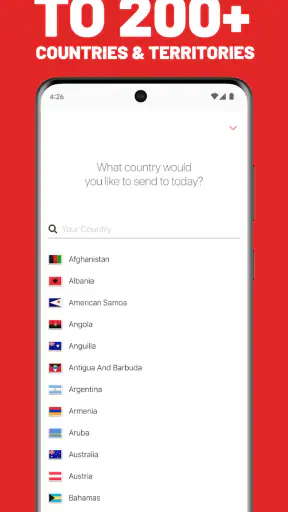
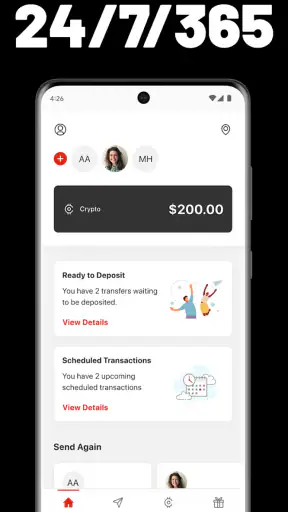
Settings and account habits worth checking
Experienced use is less about discovering secret buttons and more about making the visible settings work for you. I review my profile details, notification preferences, and saved recipient information carefully. Keeping those details current reduces repeated typing, but I would not save a recipient casually just because I expect to send money again. A saved name is convenient only when I have already checked that it matches the person’s official identification or account details.
I also check the app after installing it on a new phone or updating the operating system. The current version is 26.7.21, and it supports devices running Android 8.0 or later. I keep the app updated through the normal app-store process, but I still review a transfer from the beginning after an update rather than assuming that a familiar screen guarantees a familiar result.
Security-related habits are more valuable than cosmetic customization. I use a strong device lock, avoid entering transfer information on a shared phone, and never send a confirmation code or login detail to someone who asks for it through an unexpected message. The app can make sending money easier, but it cannot protect a user who willingly shares account access or approves a transfer they did not initiate.
Notifications deserve a practical review too. I want transaction-related updates enabled so I can notice progress or a problem, but I avoid treating a notification preview as proof that the recipient has collected or received funds. I open the app and check the transaction status when the distinction matters. That small habit prevents misunderstandings, particularly when a sender and recipient live in different time zones.
Another useful setting habit is checking the phone’s language, date, and regional conventions before entering amounts. Currency symbols can be misleading, and a familiar-looking number may be interpreted differently when punctuation changes. I slow down whenever the amount is large or the transfer is going to a country whose currency format I do not use regularly.
Faster patterns for repeat transfers
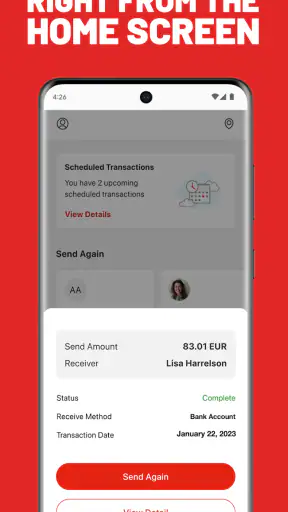
Once I have completed a transfer successfully, I build a repeatable checklist instead of relying on memory. My sequence is simple: confirm the recipient, select the destination, compare delivery methods, inspect the exchange calculation and total, then save the confirmation. Repeating the same order makes it easier to notice when one detail has changed.
Saved recipient information can speed up recurring support for a family member, but it also creates a risk of autopilot. I still compare the name and destination every time. This is one of the less obvious trade-offs of convenience: fewer keystrokes mean fewer typing errors, yet a stored recipient can make an incorrect transfer feel deceptively familiar.
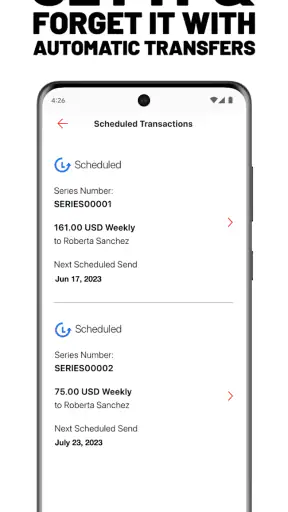
For regular monthly transfers, I keep a private note outside the app with the date, purpose, amount sent, amount received, and confirmation reference. I do not use that note as a replacement for the app’s transaction information. I use it to compare my own household budget and to answer practical questions later, such as whether I already sent this month’s support or whether a transfer was intended for rent, tuition, or groceries.
I also separate urgent transfers from planned transfers. If the recipient needs money immediately, I check the delivery option and the recipient’s ability to access it before entering payment details. If the transfer is planned, I compare the available choices calmly and avoid sending at an inconvenient moment just because the app makes the process quick. Speed is helpful, but speed can encourage careless confirmation.
Another efficient pattern is to prepare the recipient conversation first. I ask for the exact receiving name, preferred method, and location before opening the payment screen. This avoids starting a transfer, discovering that the recipient cannot use the selected method, and then having to rethink the transaction halfway through. It is a small workflow improvement, but it makes the app feel considerably less stressful.
Where the app is strong, and where it creates friction
Its main strength is reach and familiarity. MoneyGram is recognizable to people who may not want to open a digital bank account or connect their finances to a newer payment service. The app also gives me a way to start an international transfer remotely, which is more convenient than making every transaction in person.
The interface is most valuable when I already understand the transfer I want to make. It guides me through the necessary choices, but it cannot decide whether the recipient should collect cash, receive a deposit, or use another available option. New users may still need to read each screen carefully because financial terminology and delivery conditions are not as forgiving as ordinary shopping checkout.
The biggest friction is not necessarily tapping through the form. It is comparing the real value of one option with another. Fees, exchange rates, delivery methods, and payment arrangements can all affect the result. I would not choose the app solely because it is free to install. The relevant question is how much the recipient receives after the complete transfer calculation.
This is where the usual alternatives can be better. A bank transfer may suit someone who already has a low-cost international banking route and does not need cash pickup. A digital wallet may be quicker for two people already using the same service, while a local agent may be preferable for a person who wants face-to-face help or has limited smartphone access. MoneyGram’s advantage is flexibility across familiar remittance situations, not a promise that it will always be the cheapest or simplest choice.
I would also skip it for casual domestic payments between friends if both people already use an instant local payment method. Adding an international money-transfer service to a simple lunch reimbursement creates unnecessary steps. Likewise, I would not use it as an investment platform, a spending tracker, or a place to hold a general travel balance. Its purpose is much narrower and clearer: moving money to another person through supported transfer routes.
Limits that experienced users should respect
International transfers involve identity, destination, payment, and recipient requirements, so I never assume that a process that worked once will work identically every time. A country, delivery method, or recipient situation can change the available choices. I review the final details rather than reusing an old mental estimate.
I am also careful with cancellation expectations. If I notice a mistake, I contact the appropriate support channel as soon as possible and keep the confirmation information ready. I do not tell myself that an error will automatically be easy to undo, particularly after the recipient has begun the collection or delivery process. The practical lesson is simple: prevention is more dependable than correction.
Cash pickup deserves extra caution. I explain to the recipient that they should use the correct transfer information and their valid identification, and I avoid sharing those details broadly. A transfer reference is not something I post in a group chat or send to an unverified intermediary. Convenience should never turn into careless distribution of sensitive information.
For larger or especially important transfers, I use a two-person check. I read the recipient’s name and amount aloud to someone I trust, or I compare them against the original message from the recipient before confirming. This may sound excessive for a familiar contact, but it is useful when several family members have similar names or when currency conversion makes the amount look unfamiliar.
The app is rated for Everyone, which makes it broadly accessible as a mobile finance tool, but an age label does not remove the need for adult judgment around money. I would teach a younger user how to recognize scams and protect login information before allowing them to participate in a transfer. The financial consequences of a mistake are real even when the software is easy to operate.
Who will get the most from it
I recommend MoneyGram® Money Transfers App to people who regularly send money internationally and value access to multiple delivery possibilities. It is particularly practical when the recipient may need cash pickup, when the sender wants to begin the process from a phone, or when both sides are comfortable confirming details themselves.
It is also a good fit for families who have developed a consistent monthly routine. The app can reduce repeated trips and typing, provided the sender continues to verify the recipient and total instead of treating each transfer as automatic. That combination of convenience and caution is what makes it useful over time.
I would point first-time users toward it when they are willing to compare the final cost and communicate clearly with the recipient. I would not recommend it to someone who expects every international payment service to show one universal price or instant access in every situation. The right choice depends on the destination, delivery method, and the recipient’s practical needs.
My final assessment after using the workflow
MoneyGram® Money Transfers App succeeds because it focuses on a familiar problem and makes the initial transfer possible from a mobile device. Its free availability and long presence in the finance category make it easy to try, while the strong average rating and more than 52 thousand written reviews indicate that many users have found it useful. I see it as a practical remittance tool, not an all-purpose financial companion.
My best advice is to use it deliberately: prepare the recipient’s details, compare the amount paid with the amount received, choose the delivery method around the recipient’s reality, and keep the confirmation information. For repeat transfers, create a checklist and a private record, but never let saved information replace a final verification.
The app is not automatically the best option for every payment. A bank, wallet, or local transfer service may win on cost or simplicity in a particular situation. Still, when international reach, cash access, and a recognizable transfer process matter more than having the absolute lowest possible fee, I consider this a dependable option worth keeping on my phone.
MoneyGram® Money Transfers App FAQ
What can I do with the MoneyGram® Money Transfers app?
The MoneyGram® Money Transfers app lets you arrange international and domestic money transfers from a mobile device. Depending on your location, you may be able to send money to a bank account, mobile wallet, debit card, or a participating cash-pickup location. The app also provides transfer tracking, recipient details, exchange-rate information, and access to available payment methods before you confirm a transaction.
How much does it cost to send money with MoneyGram?
The total cost depends on several factors, including the destination country, transfer amount, delivery method, payment method, and current exchange rate. The app normally displays the transfer fee, exchange-rate details, and the amount the recipient should receive before you submit the payment. Because prices can vary, review the final summary carefully rather than relying on a general fee estimate.
What information is required to send money through the app?
You generally need to create or access a MoneyGram account and provide accurate sender and recipient information. Requirements may include your legal name, address, date of birth, identification details, recipient’s full name, destination, and preferred delivery method. Additional verification can be requested for security or regulatory reasons, so the information must match official documents and the recipient’s identification.
How long does a MoneyGram transfer take, and can I track it?
Delivery time varies according to the destination, selected service, payment method, compliance checks, weekends, holidays, and whether the recipient chooses cash pickup or an account deposit. Some transfers may be available quickly, while others take longer. After sending, you can usually follow the transaction status in the app using the reference number and transfer details.
Is the MoneyGram app safe to use, and what should I watch for?
The app includes account-security and transaction-verification measures, but users should still protect their login information and device. Download it only from an official app store, use a strong unique password, and review recipient details before paying. Never send money to someone who pressures you, promises a prize, or asks for payment through an unexpected message, since completed transfers can be difficult to reverse.











